Thank you! Expect our reply within the next 48 hours!
Something went wrong while submitting, please try again.
Unsubscribe anytime. We’ll only email when we have something useful to share.
Bookkeeping for Landscaping Businesses
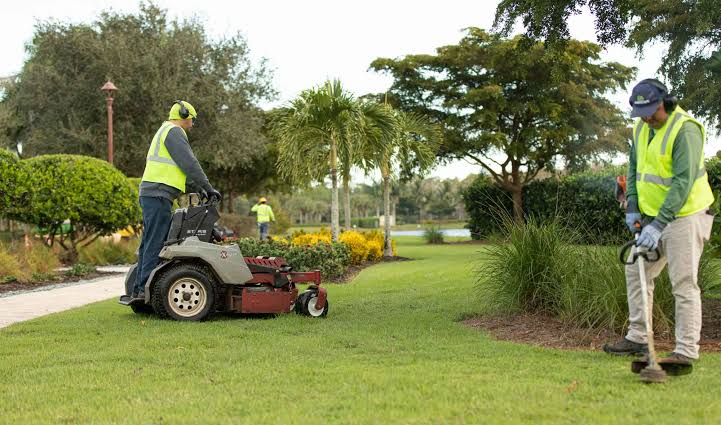
A lot of landscaping business owners know their margins are getting tighter before they can explain why.
The pressure usually shows up first in the day-to-day operation. Crews are busy, jobs are getting completed, revenue may look healthy, but there seems to be less money left over at the end of the month.
Pricing may not feel as profitable as it used to. Labor costs keep climbing. Materials cost more. Equipment and fuel expenses add up. A job that looked profitable when it was sold may not look nearly as good once the actual costs come in.
That usually means the financial reports are capturing the result, but they are not giving leadership enough structure to understand the cause.
A landscaping company's P&L can show that gross profit has declined without making it obvious what changed underneath it.
Labor, materials, subcontractors, fuel, equipment, and other job-related costs can sometimes be grouped into broad categories. While the accounting may technically be correct, that level of reporting may not tell the owner what they actually need to know.
For example:
When those costs are too broadly grouped, leadership sees the margin compression but has a harder time identifying where it is coming from.
One of the biggest challenges for landscaping companies is that being busy does not necessarily mean being profitable.
A company can have crews working every day, multiple projects underway, and strong revenue coming in while profitability continues to decline.
Consider a landscaping company that takes on several large installation projects.
The jobs generate significant revenue, but crews require more hours than originally estimated. Material prices increase. Additional deliveries are needed. Equipment stays on the job longer than expected.
From the outside, the business looks busy and successful.
But when the actual costs are compared with what was originally expected, the margin tells a different story.
Without consistent financial and job-cost reporting, those differences can be difficult to see until the work is already completed.
Once the financial picture becomes unclear, conversations can turn into guesswork.
An owner may wonder:
"Do we need to raise our prices?"
But the real issue might be labor hours.
Or:
"Are materials getting too expensive?"
But the bigger problem might be estimating or job efficiency.
Or:
"Why aren't we making more money when revenue is up?"
The answer could be that certain jobs, services, or customers are generating much less margin than expected.
When reporting does not clearly separate these factors, owners can end up making broad decisions when the actual problem is much more specific.
That delay matters.
The longer margin pressure goes unexplained, the more difficult it becomes to correct pricing, labor allocation, estimating, purchasing, or job-management issues before they affect additional work.
Margin reporting becomes much more useful when costs are organized around how a landscaping business actually operates.
That does not mean creating hundreds of accounting categories.
It means making the important cost drivers visible.
For a landscaping company, that may include separating costs such as:
The goal is to make it easier to see what changed and why.
If labor is running higher than expected, that should be visible.
If material costs are increasing, leadership should be able to identify it.
If one type of project consistently produces lower margins than another, the reporting should help bring that pattern to the surface.
For landscaping businesses, looking only at the company's overall P&L may not be enough.
A company can be profitable overall while individual jobs are producing very different results.
One project might have strong margins because the estimate was accurate and the crew completed the work efficiently.
Another might generate similar revenue but produce significantly less profit because labor hours, materials, or subcontractor costs ran higher than expected.
When those differences are visible, owners can begin asking better questions:
What did we estimate?
What actually happened?
Where did the difference come from?
Was it pricing, labor, materials, scope changes, or job efficiency?
Those questions create a much more useful margin conversation than simply looking at whether total revenue went up or down.
This is where stronger financial operations support can make a difference.
Good bookkeeping is not just about recording transactions and closing the books.
For a growing landscaping business, financial reporting should help connect the numbers to the way the business actually operates.
That can mean cleaner cost mapping, consistent month-end review, better visibility into job-related expenses, and clearer explanations of why margins are changing.
Instead of simply saying, "profit is down," leadership can start asking:
"Which costs changed, where did they change, and what should we do about it?"
That is a much more useful conversation.
Most landscaping business owners do not need another complicated dashboard.
They need a clearer answer when profitability starts to move.
When labor, materials, subcontractors, equipment, and other key costs are structured in a way that reflects the business, financial reporting becomes easier to understand and more useful for decision-making.
The goal is not simply to know whether the business made money.
It is to understand where the margin came from, where it went, and what can be done about it.
For a landscaping business, that can mean making better pricing decisions, catching cost increases earlier, improving estimates, and identifying which work is actually contributing to the bottom line.
Your financial reports should do more than tell you that margins changed. They should help you understand why.
Book a strategy session with JADDE Financial Solutions:
https://calendly.com/jaddefs/intro-call

Q: “How can I tell if my business is profitable?” This is a question we hear a lot. It can be difficult to get a handle […]

Sometimes we just need to slow down. It could be our body telling us it needs a break. It could be our mind experiencing the […]
As a contractor, you probably didn’t get into the business because of a love of working with numbers. Working with […]
In a 30–45 minute free intro call, we'll learn about your business, review your current setup, and outline the fastest path to accurate, on-time numbers.